Contents
The announcement does not impose one universal duty in 2028. The government plan assumes legislation in 2026 and a one-year preparation period, followed by phases from 2028 through 2030 according to workplace size. A later enactment date or different final text could change both timing and application.
- Current status
- Government plan · legislation still required
- Conditional phases
- 100+ employees in 2028 · 10–99 in 2029 · under 10 in 2030
- Proposed scope
- Benefits accruing after each phase begins
- Fact-checked
- November 17, 2026, 09:18 KST · official MOEL sources
The November 16 meeting still described legislation as necessary
Korea’s Ministry of Employment and Labor convened a labor-management-government task force at 08:00 KST on November 16. Its release says most of the agenda requires legal amendments and that the parties agreed to cooperate through the legislative process.
The October 29 plan therefore should not be presented as law already in force. As of this article’s check time, the official materials did not show completed legislation, final implementing rules or an individual conversion application.
The 2028–2030 sequence is a conditional rollout proposal
The October 29 plan assumes legislation during 2026 and one year of preparation. On that assumption, mandatory retirement-pension coverage would start with workplaces of at least 100 employees in 2028, move to those with 10–99 employees in 2029, and reach workplaces with fewer than 10 employees in 2030.
Workplace size is the proposed phase boundary, not a proxy for an employee’s balance. If enactment is delayed or the final statute differs, the dates and size bands can change. Do not save the years as unconditional deadlines.
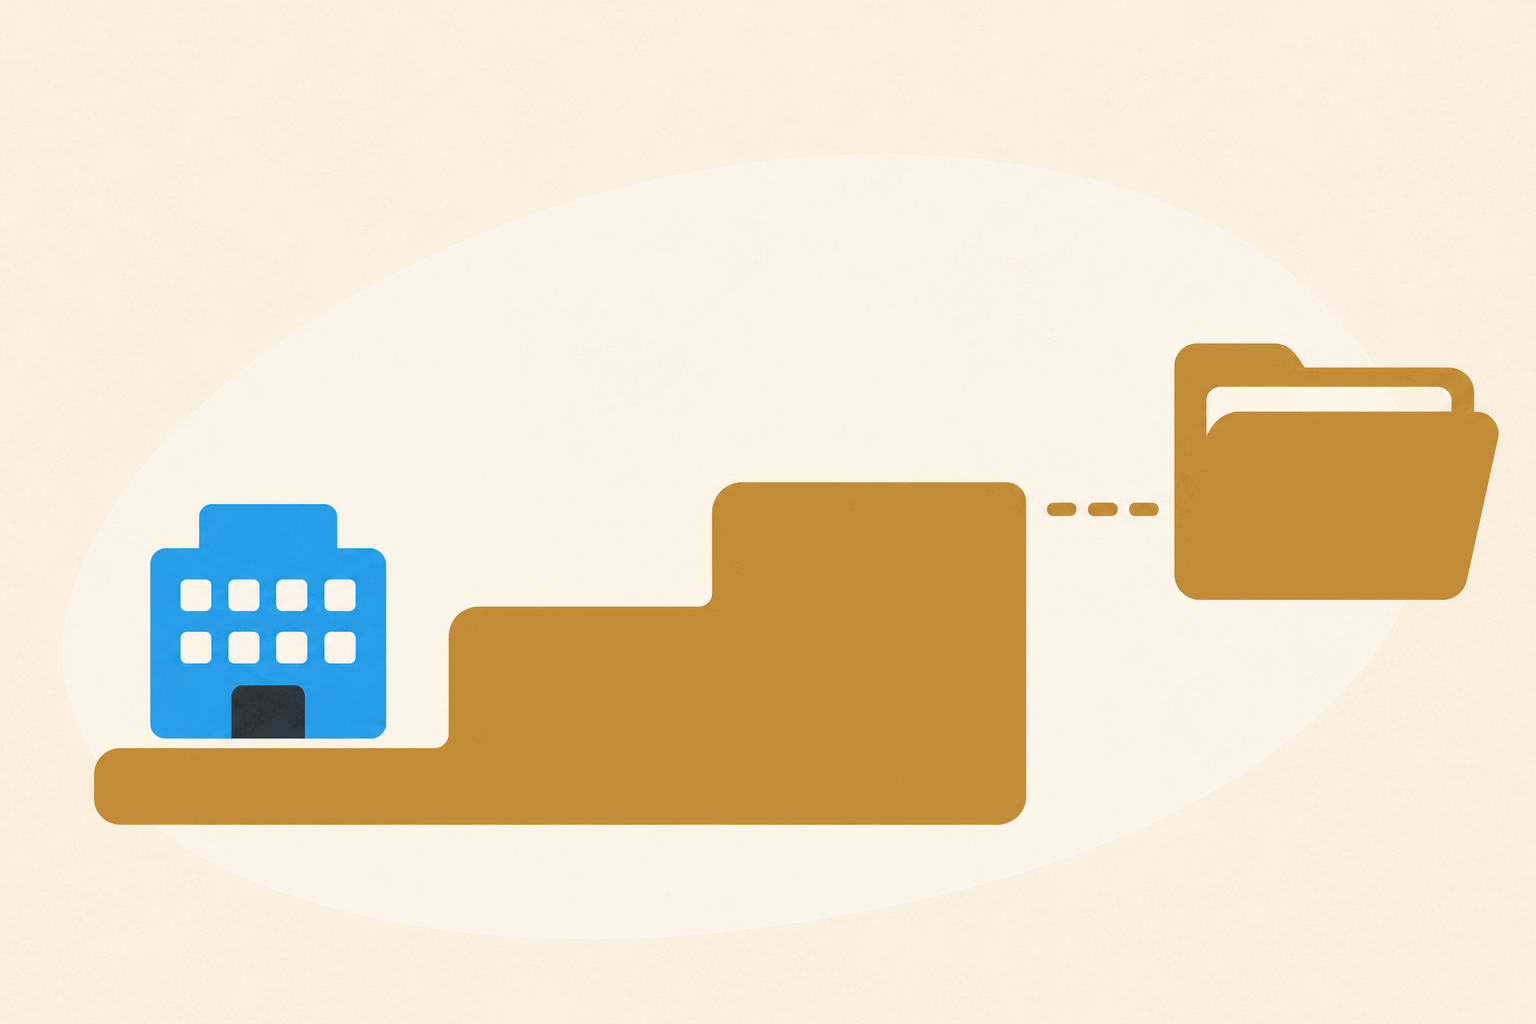
| Proposed phase | Workplace size | Important condition |
|---|---|---|
| 2028 | 100 or more employees | Assumes 2026 legislation and preparation |
| 2029 | 10–99 employees | Recheck the final statute and effective date |
| 2030 | Fewer than 10 employees | Not a current mandate |
The proposal starts with benefits accruing after each effective date
The government explanation says retirement benefits newly accruing after a workplace enters its phase would be funded through a retirement-pension arrangement. It does not say that all benefits accumulated for service before that date would automatically be transferred at once.
An individual’s actual accrual and transfer treatment would depend on the enacted statute, the workplace plan and employment records. This article does not calculate a balance before those rules exist.
Existing contract-based plans are not being abolished
MOEL’s November 3 Q&A says the existing contract-based retirement-pension system would remain while fund-based options are added. Additional options do not mean current defined-benefit or defined-contribution arrangements disappear immediately.
Employees can first check whether their workplace currently uses statutory severance pay, a DB plan or a DC plan. A policy announcement alone is not a reason to close or transfer an individual account.
The arrears problem explains the policy, but does not create a guaranteed return
MOEL says unpaid retirement benefits represented 41.1% of wage arrears in 2025, totaling KRW 822.9 billion. The Korean figure is KRW 8,229 eok, which independently converts to KRW 822.9 billion. It is evidence for the policy problem.
That aggregate does not predict a particular worker’s loss or a new plan’s investment return. The policy objective, legal entitlement and product performance remain separate questions.
What can be checked now is the current plan and the legislative record
Employees can review the workplace retirement-benefit rules, provider, DB or DC status and recorded balance. If payroll, workplace and provider records differ, ask the employer and responsible labor office about the arrangement currently in force.
Later, verify whether the National Assembly passed the law, its promulgation and effective dates, and the rule for measuring workplace size. Keeping proposal, enactment and implementation separate prevents an announced plan from becoming a false current entitlement.
Frequently asked questions
Will every Korean workplace have to join in 2028?
No. The proposal starts with workplaces of at least 100 employees and depends on legislation and preparation. It is not a current duty.
Will benefits for all past service move into a pension plan?
The government describes applying the change to benefits accruing after each phase begins. The enacted law and workplace rules would control the final treatment.
Should an employee open a new account now?
No. These releases concern a policy plan and legislative talks. Check the current arrangement and wait for enacted and effective rules.
Summary
Korea proposed universal workplace retirement-pension coverage in phases from 2028 to 2030, but legislation is still required. The timetable assumes a 2026 enactment and preparation, with the change applying to benefits accruing after each phase begins.